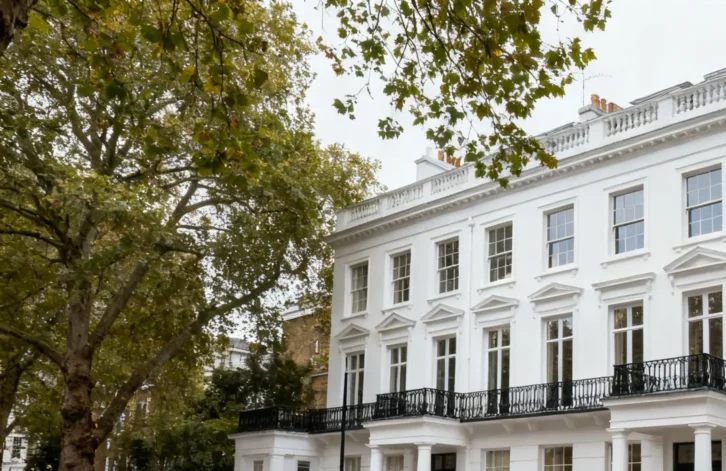
Tax specialists have raised questions about the stamp duty paid on the £265 million sale of Providence House in Chelsea, Britain’s most expensive residential property transaction.
Property developer Nick Candy sold the property in May to hedge fund manager Suneil Setiya. Analysis by London Centric and Tax Policy Associates suggests the transaction structure may have reduced the stamp duty liability by approximately £18.5 million.
Transaction structure
According to Dan Neidle, founder of Tax Policy Associates, a standard £265 million house purchase would typically incur £32 million in stamp duty. However, the research indicates that approximately £13 million was paid on this transaction.
The property was sold through Providence House LLP, incorporated on 11 October 2024 by Candy, his wife Holly Valance, and a second LLP whose members are two long-standing Candy advisers. The sale included five additional flats that Candy had previously transferred into the LLP.
This structure enabled the transaction to be classified as commercial rather than residential, applying a 5% rate instead of the 12% residential rate. The approach is based on the Finance Act 2003, which states that where six or more separate dwellings are subject to a single transaction involving the transfer of a major interest, they are treated as non-residential property for stamp duty purposes.
Market implications
Neidle stated: “We think it will be of public interest that the most expensive house in British history was acquired using such a structure. And there’s an important question: did the structure work? Or will HMRC be able to recover the £18.5 million?”
He added that if HMRC cannot recover the amount, the scheme may be adopted by other buyers of high-value properties until authorities close the loophole. The approach highlights ongoing debates about tax efficiency in the property sector, which has seen increased scrutiny of commercial property transactions in recent months.
The parties involved believe the correct amount of stamp duty was paid. Setiya declined to comment, and Candy has been approached for comment.
Regulatory context
The case emerges as property transactions face greater regulatory attention, with industry professionals monitoring potential policy changes that could affect high-value deals.
The outcome of any HMRC review could establish precedents for similar transactions in the prime London market and beyond, particularly as buyers and their advisers seek tax-efficient structures for large-scale property acquisitions.