A London family has been waiting three years for LV= General Insurance to complete repairs on their home following a subsidence claim, highlighting growing challenges in the property insurance sector as such claims increase across the UK.
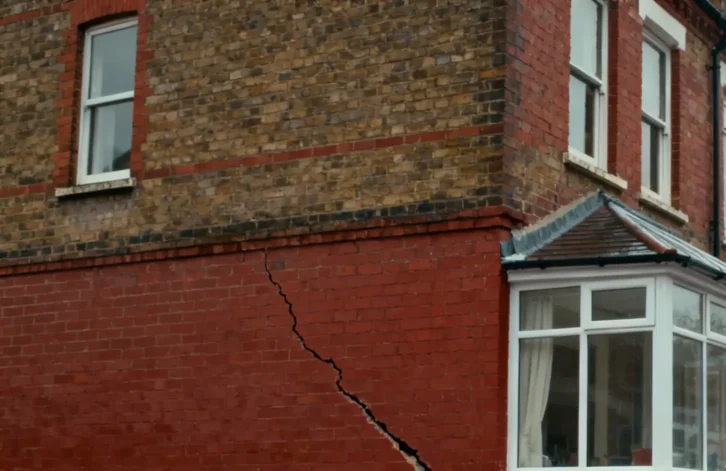
The homeowners lodged a claim for subsidence damage to their extension and conservatory in 2023. According to the family, independent experts recommended repairs, but the insurer has proposed alternative methods that they consider inadequate. Three years into the claim process, cracking in interior walls has reportedly caused a radiator to detach.
The case reflects broader trends affecting property owners and the insurance market. Subsidence claims have been rising as repeated droughts cause soil shrinkage, a problem accelerated by nearby trees. The family removed several trees on LV=’s advice, but the damage continued.
Insurance response and timeline
LV= obtained a quote for underpinning in February but did not proceed with the work at that time. An independent surveyor commissioned by the homeowners in May concluded that the damaged extension required underpinning or rebuilding. The insurer has since acknowledged that cracks have worsened and a full rebuild is necessary.
A spokesperson for LV= stated: “Subsidence claims can be protracted because the most important step is to address the cause of movement, in this case tree removal, before permanent repairs can be undertaken.” The company attributed the delay to a eucalyptus tree on neighbouring property, with the owner refusing removal.
The insurer confirmed that repairs will begin once designs and council approvals are complete. LV= said it takes the claim seriously and understands the frustration over the timeline.
Premium increase dispute
The family’s annual premium increased from £400 to £2,500 during the claims process. LV= is reviewing the premium rise under its complaints procedure.
The situation illustrates challenges facing both homeowners and insurers in managing subsidence claims. As property values face pressure in some London markets, maintenance and insurance issues add further complexity for homeowners. The case also comes as the UK property sector experiences broader changes affecting both owners and tenants.
The extended timeline for subsidence claims reflects the technical complexity of addressing underlying causes before permanent repairs can proceed, though homeowners increasingly question whether delays serve legitimate purposes or represent cost management strategies by insurers.